A Quebec Contractor Paid a French Professional Indemnity Rate But Was Defended Under New York Law
A general contractor based in Laval, Quebec, bought a professional indemnity policy that seemed like a bargain. The premium was roughly 20 percent lower than any domestic quote the broker had found. The policy was placed through a Lloyd's panel, priced using French actuarial tables, and its wording specified that New York law would govern any dispute. The contractor, who routinely bid on projects across Quebec and Ontario, signed the binder without reading the choice-of-law clause. Fifteen months later, a subcontractor's injury at an Ottawa job site triggered a claim that would expose the gap between the premium paid and the protection delivered.
The Quebec Contractor's Policy Crossed Three Jurisdictions
The policy sat at the intersection of three legal and regulatory systems. The risk itself was a Quebec-based construction firm. The premium was calculated using loss data from the French professional liability market, where a centralized tariff bureau publishes standard rates for trades. The policy wording, however, incorporated New York law as the governing jurisdiction—a clause that would determine everything from the statute of limitations to the standard of care applied in a coverage dispute.
This kind of jurisdictional stacking is not unusual in the wholesale insurance market. Brokers with multinational binding authority can access capacity from London, Bermuda, or European carriers that offer rates based on their home-market assumptions. In this case, the broker—a Montreal-based wholesaler with a Lloyd's coverholder—found a French carrier willing to write the risk at a rate that undercut domestic carriers by a wide margin. The French rate reflected a claims environment where professional liability suits are less frequent and damages are typically lower than in North America.
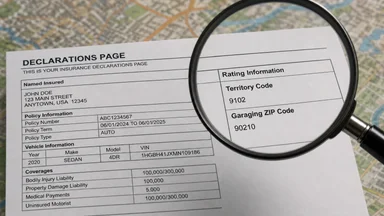
The contractor never received a disclosure document explaining the implications of the foreign governing law. Quebec's insurance regulator, the Autorité des marchés financiers, does not require a policy filed in another jurisdiction to be reviewed for local compliance if it is placed through a licensed broker. The policy was never filed in Quebec. It existed in a regulatory blind spot—priced like a French risk, governed like a New York contract, and covering a Canadian operation.
The claim that eventually arose—a subcontracted electrician's fall from a ladder at an Ottawa commercial site—would test every seam in this patchwork. The injured worker sought damages under Ontario's Occupational Health and Safety Act, which imposes strict liability on the general contractor. The policy's French-form wording had no Canada-specific endorsement, and the New York choice-of-law clause meant a Manhattan-based firm would control the defence.
Why a Quebec Risk Priced on French Loss Data
The French professional indemnity market operates differently from the Canadian or American markets. In France, the Fédération Française de l'Assurance publishes standard tariff tables for many trades, including construction professionals. These tables are built on pooled loss data from the entire French market, which has a lower frequency of claims and smaller average settlements compared to Canada. A typical French professional liability claim for a minor construction defect might settle for €15,000 to €30,000, whereas a similar claim in Ontario can exceed CAD $100,000 once legal costs are included. Quebec, by contrast, lacks a comparable centralized loss-history pool for small contractors. Domestic carriers rely on their own experience, which is often thin for individual trades. The result is a higher base premium, sometimes 30 to 50 percent above what a French carrier might charge for a risk that appears similar on paper. The broker in this case accessed a Lloyd's panel that had negotiated a block of capacity underwritten by a French insurer. The panel's pricing algorithm used French loss curves adjusted by a flat territorial multiplier—a crude factor that did not account for the specific differences between Quebec and Ontario liability regimes.
The contractor paid roughly CAD $12,000 for a CAD $1 million limit, compared to quotes of CAD $15,000 to $16,000 from Canadian carriers. But the saving came with embedded assumptions. The French rate assumed that claims would be handled in a civil-law environment with capped damages and no punitive awards. New York law, however, permits punitive damages in certain professional liability cases, and the Ontario project site exposed the contractor to a common-law system with higher defence costs. Regulatory arbitrage of this kind is not illegal, but it relies on a gap in oversight. Quebec's Autorité does not require a foreign insurer to file rates or forms if the policy is placed through a licensed broker and the carrier is not domiciled in Canada. The broker's duty to advise the client on the implications of a foreign governing law is not explicitly codified. The contractor later told his broker that he had assumed "all policies are basically the same."
New York Defence Counsel Controlled the Response
When the claim was reported, the insurer appointed a New York City-based law firm to handle the defence. The firm specialised in construction liability under New York law, but the accident had occurred in Ontario, where the Occupational Health and Safety Act imposes a different duty on contractors. The defence counsel had to learn Ontario's statute on the fly, billing the policy's defence cost pool at rates typical for Manhattan—roughly $450 to $650 per hour for associates and partners.
The choice-of-law clause created a procedural mismatch. Under New York law, the statute of limitations for a negligence claim is three years from the date of injury. Under Ontario law, it is two years. The claimant's lawyer filed within the Ontario window but more than two years after the accident. The New York defence team initially argued the claim was time-barred under New York's three-year rule, but a New York court applying New York choice-of-law principles determined that Ontario's limitation period was substantive and should apply. The motion to dismiss failed, and the defence costs incurred on that motion alone exceeded $30,000.
The specific legal conflict was that Quebec's civil law, which the contractor understood, is based on codified principles and written contracts, while New York's common law relies on precedent and judicial interpretation. The policy's wording, drafted in English using common-law terms like "occurrence" and "personal injury," was unfamiliar to the contractor, who had signed a French-language summary at binding. When the insurer denied coverage for the subcontractor's claim—arguing that the policy excluded "work performed in Canada"—the contractor had to rely on a New York lawyer to interpret a clause that had never been tested in a Canadian court.
The contractor paid a CAD $5,000 deductible as stated in the policy, but he lost control of the defence strategy. The insurer had the right to select counsel and settle claims without his consent. By the time the case was resolved through a mediation that produced a CAD $250,000 settlement, the defence costs had eaten up roughly CAD $180,000 of the CAD $1 million limit. The contractor's own legal fees for monitoring the coverage dispute added another CAD $15,000. The net indemnity available for the settlement was just CAD $820,000, leaving the contractor personally exposed for the difference if the claimant had pressed for more.
The Ontario Claim Triggered a Coverage Gap
The policy's territorial clause excluded Canada unless specifically endorsed, and no such endorsement was issued. The French-form wording included a standard clause covering "work performed in any country within the European Economic Area and such other territories as agreed by the insurer." The broker had obtained a verbal agreement from the underwriter to extend coverage to Canada, but no written endorsement was issued. When the claim arose, the insurer argued that the verbal agreement was not binding and that the policy's exclusion for "operations outside the EEA" applied.
The exclusion was not visible in the French-language summary the contractor had received. The full policy wording, which ran to 47 pages, was provided only in English. The contractor's reading of the summary had led him to believe that the policy covered all of North America. The broker's file notes, later produced in discovery, showed that the underwriter had said "we can do Canada" during a phone call, but no one had followed up with a formal endorsement.
The New York court, applying New York law, interpreted the ambiguity against the policyholder. Under New York precedent, verbal agreements to modify an insurance contract are generally unenforceable unless the policy expressly permits them. The court found that the policy's "entire agreement" clause barred any reliance on oral representations. The coverage for the Ontario claim was denied, and the contractor was forced to fund his own defence and settlement out of pocket.
The gap was not just about territorial scope. The policy's definition of "professional services" was tied to French regulatory categories that did not match Quebec's licensing system. The contractor's activities—general contracting, project management, and subcontractor supervision—fell under a different classification in Quebec than in France. The insurer argued that some of the contractor's duties, such as on-site safety inspections, were not "professional services" as defined by the policy. The court agreed, further narrowing the coverage.
By the time the case settled, the contractor had incurred total losses of roughly CAD $350,000—the deductible, his own legal fees, and the uncovered settlement. He had saved approximately CAD $3,000 per year on premium over three years, a total saving of CAD $9,000. The net financial impact was a loss of CAD $341,000. The experience led him to file a complaint with the Quebec Autorité, which has since opened an inquiry into cross-border placements by Lloyd's coverholders.
Three Lessons for Cross-Border Professional Buyers
First, verify the choice-of-law clause matches the risk location. A policy governed by a foreign law may apply procedural rules—statutes of limitation, standards of proof, remedies—that differ from the law of the place where the claim arises. In this case, New York law allowed the insurer to deny coverage based on a technical reading of the territorial clause, whereas a Quebec court might have applied the principle of good faith more broadly to protect the policyholder. Buyers should ask their broker to explain which jurisdiction's law will govern and whether that jurisdiction's courts have handled similar coverage disputes.
Second, ask whether the premium reflects the local claims environment. A rate based on French loss data assumes a claims pattern that may not hold in Canada. Defence costs in Ontario are typically higher than in France, and the frequency of claims is greater. Buyers should request a breakdown of the rating factors used to set the premium, including the territorial multiplier and the source of the loss data. If the broker cannot provide a clear answer, that is a red flag.
Third, demand access to a Canadian defence panel. A policy that requires defence under a foreign law may force the policyholder to accept counsel chosen by the insurer, often at higher rates. Buyers should negotiate a clause that allows them to select a defence firm licensed in the jurisdiction where the claim arises, with the insurer's consent not to be unreasonably withheld. This can reduce defence costs and improve the quality of the defence.
Finally, check the regulatory filing status of the policy in the home province. If the policy is not filed with the local regulator, the policyholder may have limited recourse if the insurer denies coverage. Brokers with multinational binding authority should provide a written disclosure that explains the implications of a non-admitted placement. The Quebec Autorité's upcoming guidance may require such disclosures as a matter of law.
How AI Could Prevent Such Jurisdictional Arbitrage
Artificial intelligence is beginning to address the kind of cross-jurisdictional mismatch that caught the Quebec contractor. As noted by Risk & Insurance in July 2026, the property and casualty market is actively adopting AI to surface critical insights from unstructured data, allowing claims professionals to reduce leakage. In the underwriting phase, AI tools can ingest policy language and jurisdictional rules to flag clauses that may conflict with the risk's actual location. A system trained on thousands of policy wordings and court decisions could have identified the territorial ambiguity before the policy was bound. For example, a tool could parse the policy's territorial clause and compare it against the contractor's known project locations in Quebec and Ontario, automatically flagging the absence of a Canadian endorsement and prompting the broker to obtain one.
Gallagher Re's mid-year 2026 report, also cited by Artemis.bm, notes that the retrocession market is softening, with catastrophe loss rates falling by up to 20 percent for loss-free accounts. This softening may increase competition among carriers, potentially encouraging more cross-border placements. AI-based compliance checks could become a differentiator for brokers who want to avoid the reputational risk of a coverage gap. A tool that automatically compares the policy's choice-of-law clause against the risk's operational footprint—covering all 50 US states and multiple Canadian provinces—could reduce the chance of an unendorsed territorial gap.
In claims, AI can detect when a policy's governing law differs from the law of the claim jurisdiction and alert the claims handler to potential conflicts. Automated checks across more than 50 regulatory regimes could ensure that statutes of limitation, notice requirements, and coverage triggers are handled consistently. The Quebec contractor's case might have been avoided if a system had flagged that the policy's New York choice-of-law clause conflicted with Ontario's limitation period and the Quebec civil code's treatment of verbal agreements. AI could also assist in real-time monitoring of verbal agreements, prompting underwriters to issue endorsements immediately after a phone call, reducing the risk of unrecorded promises.
Of course, AI is not a panacea. The tools are only as good as the data they are trained on, and many legacy policies are still in paper or PDF form. But the trend is clear: as the market softens and cross-border placements increase, the demand for automated jurisdictional compliance will grow. Brokers who invest in these tools now may capture a larger share of the multinational middle-market business that is currently underserved.
What Regulators Might Do Next
Regulatory responses to cross-jurisdictional arbitrage are emerging on both sides of the border. The Massachusetts Supreme Judicial Court, in a decision covered by Risk & Insurance in July 2026, upheld the insurance commissioner's authority to reject rate changes that lack adequate justification. While that case dealt with workers' compensation rates, the principle—that rates must be supported by local data—could extend to professional liability. If a carrier prices a Massachusetts risk using French loss data, the commissioner might demand a showing that the rates are not unfairly discriminatory.
In Quebec, the Autorité des marchés financiers is considering a rule that would require any policy covering a Quebec-based risk to include a Quebec choice-of-law clause unless the policyholder signs a specific waiver. The rule would apply to placements through licensed brokers, including Lloyd's coverholders. The Quebec contractor's complaint has accelerated the timeline; a draft is expected by early 2027.
Ontario's Financial Services Regulatory Authority (FSRA) is reviewing cross-border marketing practices, particularly for commercial lines sold to small and medium enterprises. A consultation paper released in June 2026 raised concerns about policyholders being unaware of the legal framework governing their coverage. FSRA may require brokers to provide a plain-language summary of the governing law and its implications before binding.
At the European level, the Insurance Distribution Directive (IDD) could extend to placements of European carriers covering non-European risks. If the IDD's conduct-of-business rules are applied to cross-border placements arranged through Lloyd's, the broker would be required to disclose the governing law and any material differences from the law of the policyholder's home country. The European Insurance and Occupational Pensions Authority (EIOPA) is studying the issue.
The National Association of Insurance Commissioners (NAIC) in the US has formed a working group on choice-of-law standards in commercial insurance. The group is expected to issue a white paper in 2027 recommending uniform disclosure requirements for policies that select a governing law different from the risk's principal location. While the NAIC's recommendations are not binding, they often influence state legislation.
For buyers, the key recommendation is to insist on a policy that aligns governing law with the primary risk location, and to obtain written endorsements for any territorial extensions. Brokers should proactively disclose the implications of foreign governing laws and maintain records of all oral agreements. Regulators should consider requiring that non-admitted policies include a mandatory disclosure statement, similar to the warnings on financial products, highlighting the risks of jurisdictional mismatches. Until such safeguards are universal, buyers must remain vigilant and demand transparency at every step of the placement.
This article is for informational purposes only and does not constitute legal or insurance advice. Readers should consult a qualified professional regarding their specific circumstances.