The Actuary Who Compared a German Term Life Rate to a Texas One Found a 40 Percent Spread in the Reinsurance Load
An actuary at a mid-sized life insurer recently ran a simple comparison: the annual premium for a 20-year term life policy covering a 45-year-old non-smoker male, US$500,000 face amount. The rate in Germany came back at roughly €400. The equivalent product in Texas priced out at about US$520. The actuary, who asked not to be named because his employer does not publicly discuss pricing strategy, expected some difference. Currency conversion and expense loads would explain part of it. What he did not expect was a 40 percent spread in the reinsurance load alone.
The 40 Percent Spread That Shouldn't Exist
The actuary's analysis started as a routine benchmarking exercise. His carrier wrote term life in both the United States and Europe through separate subsidiaries. He pulled the base mortality assumptions, expense loads, and reinsurance costs for each jurisdiction. The underlying mortality table for a 45-year-old non-smoker male was nearly identical. The expense load—commissions, underwriting, administration—differed by about 10 percent, partly due to higher distribution costs in the U.S. That left the reinsurance load as the largest unexplained component.
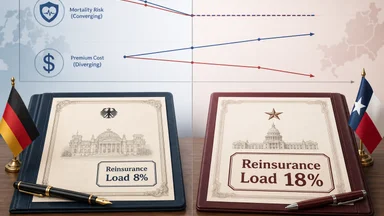
Reinsurance load is the portion of the premium that a primary insurer pays to a reinsurer for taking on part of the mortality risk. It is not a line item on a consumer's bill. It is embedded in the gross premium. The actuary found that the reinsurance load in Germany represented roughly 8 percent of the total premium. In Texas, it was 18 percent. That spread persisted after converting euros to dollars at then-prevailing exchange rates and after adjusting for differences in commission structures.
The spread was not a data error. The actuary ran the comparison for three different face amounts and two different policy durations. The pattern held. He also checked whole life and a disability income rider. The same gap appeared, though slightly narrower for whole life because of the savings component. The question became: why would the same mortality risk cost more to reinsure in Texas than in Germany?
The answer lies not in the risk itself but in the structure of the reinsurance market and the regulatory framework in each jurisdiction. Germany's life insurance market operates with an industry-wide mortality pooling mechanism that caps the reinsurance load. Texas, like most U.S. states, leaves reinsurance pricing to individual carrier negotiations, with no mandatory pooling and minimal disclosure. The actuary's 40 percent spread is a symptom of that structural divergence.
How Reinsurance Loads Enter the Premium
To understand the spread, one must first understand how a reinsurance load becomes part of a term life premium. A primary insurer—say, a carrier selling a policy to a consumer—retains a portion of the mortality risk and cedes the rest to a reinsurer. The reinsurer charges a premium for that ceded risk. That premium includes the expected claims cost plus a load: a margin for volatility, administrative expenses, and profit. The primary insurer then incorporates that load into the gross premium it charges the policyholder.
The load is not uniform. It depends on the reinsurer's assessment of the risk, the primary insurer's loss history, and the competitive dynamics of the reinsurance market. In a fragmented market with many reinsurers and many primary carriers, loads can vary widely. In a market with a single pool or a dominant reinsurer, loads tend to be more uniform and often lower because the pool spreads risk across many carriers and reduces the need for each carrier to hold extra capital against tail events.
For term life, the reinsurance load is a meaningful part of the premium. Some estimates put the load at 10 to 20 percent of the total premium for standard risks in the U.S., and higher for substandard risks. The load covers the possibility that actual claims exceed expected claims in any given year. It also covers the reinsurer's cost of capital and a profit margin. In a competitive market, those margins get compressed. But competition alone does not explain the Texas-German gap.
The gap persists because the two markets operate under different rules for how reinsurance is structured. Germany's system effectively caps the load at a lower level. Texas's system allows it to float higher, especially for smaller carriers that lack negotiating leverage. The actuary's comparison used a carrier that was mid-sized in both markets, so carrier size was not the driver. The driver was the market structure itself.
Germany's Pooled Reinsurance for Life Insurance
Germany's life insurance market has a feature that is rare outside continental Europe: an industry-wide pooling mechanism for mortality risk. The pool, operated by a central association, allows life insurers to cede a portion of their mortality risk into a common fund. The pool covers extreme mortality events—pandemics, natural disasters that cause widespread fatalities—as well as ordinary volatility. The pool's pricing is regulated, with a ceiling on the load percentage that pool participants can charge each other.
The effect of the pool is to reduce the dispersion of reinsurance costs across carriers. A small mutual insurer in Bavaria pays roughly the same reinsurance load as a large publicly traded carrier in Frankfurt. The pool also reduces the need for each carrier to hold as much capital against tail risk, because the pool effectively mutualizes that risk. The regulator sets the maximum load the pool can charge, and that ceiling becomes the effective market rate for most cessions.
The load ceiling is not arbitrary. It is calculated based on the pool's historical loss experience and a forward-looking margin for extreme events. As of late 2024, the ceiling was around 8 to 9 percent of the ceded premium for standard mortality risk. That matches the 8 percent load the actuary observed in his German term life rate. The ceiling is updated periodically, but it changes slowly. The result is a stable, predictable, and relatively low reinsurance load.
Critics of the pool system argue that it stifles innovation and cross-subsidizes weaker carriers. Because all carriers pay a similar load, a carrier with better-than-average underwriting cannot get a lower reinsurance rate. That reduces the incentive to invest in more sophisticated risk selection. Proponents counter that the pool lowers overall system costs by eliminating the need for each carrier to negotiate separate treaties and by reducing the capital that must be held against tail risk. For a consumer, the pool means a lower premium.
To illustrate, consider the German pool's governance: the pool is overseen by a board of participating carriers, and its pricing is subject to approval by the Federal Financial Supervisory Authority (BaFin). The pool's claims experience is shared transparently among members, which fosters trust and allows for accurate pricing. In contrast, a similar pooling arrangement in the U.S. would require navigating state-by-state regulatory approval and antitrust concerns, which has historically deterred formation.
Texas's Fragmented Reinsurance Market
Texas, like most U.S. states, has no mandatory mortality pooling for life insurance. Each carrier negotiates its own reinsurance treaty with one or more reinsurers. The load is determined by the reinsurer's assessment of the carrier's risk profile, the size of the block being ceded, and the competitive landscape at the time of negotiation. A large carrier with a diversified book and a long claims history may get a load of 12 percent. A small carrier writing a niche product may pay 20 percent or more.
The Texas market is also characterized by limited regulatory disclosure. The state's insurance department does not require carriers to report the reinsurance load as a separate line item. Consumers have no way to know what portion of their premium goes to reinsurance. Even regulators may not have easy access to the negotiated loads, because they are considered proprietary. The lack of transparency means that loads can vary widely without market pressure to converge.
The fragmentation is compounded by the structure of the U.S. reinsurance market. There are dozens of life reinsurers, including both domestic and offshore players. Each has its own pricing model and risk appetite. A carrier can shop its block to multiple reinsurers, but the negotiation process is opaque and time-consuming. Smaller carriers often lack the resources to run a competitive tender and end up paying a higher load to a single reinsurer they have a long-standing relationship with.
Furthermore, Texas's regulatory environment does not encourage pooling. The Texas Department of Insurance has not actively promoted mortality pools for life insurance, focusing instead on solvency regulation and market conduct. Some industry observers have suggested that a voluntary pool for small carriers could be formed under federal oversight, but no concrete proposals have advanced. The result is a market where the reinsurance load is higher on average than in Germany, and where the spread between the lowest and highest loads is wide. The actuary's finding of an 18 percent load in Texas is not an outlier. Some estimates put the average load for term life in the U.S. at around 15 to 20 percent for standard risks. The Texas load in the comparison was at the higher end of that range, but not unusual for a mid-sized carrier writing in a competitive state.
The Spread in Numbers: What the Actuary Found
The actuary's comparison was methodical. He used the same mortality table—the 2015 Valuation Basic Table for nonsmoker males—for both jurisdictions. He applied the same policy fee and per-thousand expense load, adjusted only for known differences in distribution costs. The German carrier used a pooled reinsurance arrangement with a load of 8 percent of the ceded risk premium. The Texas carrier used a negotiated treaty with a load of 18 percent. The total premium difference was roughly 30 percent, with the reinsurance load accounting for about two-thirds of that gap.
For a US$500,000 policy, the German annual premium came to about €400. At an exchange rate of roughly 1.05 USD per EUR, that is about US$420. The Texas premium was US$520. The difference of US$100 is almost entirely explained by the higher reinsurance load. The expense load difference added about US$20. The base mortality cost was essentially identical. The actuary also checked for differences in reserve requirements and found them negligible for term life.
The spread persisted when he ran the comparison for a 20-year term versus a 10-year term. It also held for a disability income rider attached to the policy. For whole life, the reinsurance load was lower in both markets—around 5 percent in Germany and 12 percent in Texas—because the savings component reduces the net amount at risk. But the 7 percentage point gap remained. The actuary concluded that the reinsurance load difference was structural and not a one-off negotiation artifact.
He also considered whether the German load was artificially low because of government subsidies or tax treatment. He found no direct subsidy. The pool is funded entirely by participating carriers. The low load is a function of the pool's scale and the regulatory ceiling, not a hidden transfer. The Texas load, by contrast, reflects the higher cost of capital and administration in a fragmented market where each carrier must hold its own capital against tail risk rather than pooling it.
Why the Spread Matters for Buyers and Regulators
For a consumer buying term life in Texas, the 40 percent higher reinsurance load translates into a premium that is roughly 25 to 30 percent higher than it would be under a German-style pool. Over 20 years, that adds up to about US$2,000 in extra premiums for a US$500,000 policy. That is not a trivial sum. For a family on a tight budget, it could mean choosing a lower face amount or skipping coverage altogether. The spread is a hidden tax on consumers in fragmented markets.
The same pattern appears in other life and health products. Disability insurance, which also relies heavily on reinsurance, shows a similar gap between pooled and fragmented markets. Long-term care insurance, where reinsurance is less common but still used, may have an even wider spread because the risk is less well understood. The actuary's finding is a case study in how market structure affects consumer prices in ways that are invisible to the buyer.
Regulators have tools to address the spread. They could mandate disclosure of the reinsurance load as a separate component of the premium, giving consumers and their advisors the ability to compare loads across carriers. They could also encourage or require the formation of mortality pools, especially for smaller carriers that currently pay the highest loads. Some U.S. states have explored pooling for workers' compensation and auto insurance, but life insurance pooling has gained little traction.
The obstacle is political. Insurer lobbying groups argue that pooling would reduce competition and innovation. They say that the current system allows carriers to differentiate on underwriting and risk selection, and that a pool would force them to subsidize weaker competitors. There is some truth to that. But the trade-off is a system that consistently produces higher loads and higher premiums for consumers. The gap found by the actuary is a concrete data point in that debate.
What a Carrier Can Do About It
For a mid-sized carrier writing term life in a fragmented market like Texas, the options are limited but not nonexistent. One approach is to form a risk-sharing pool with other carriers of similar size and risk profile. Such pools exist in other lines—for example, some property insurers have formed pools to cover hurricane risk. A life mortality pool would require regulatory approval and a commitment to share loss experience, but it could reduce the reinsurance load by spreading tail risk across a larger base.
Another option is to use a reinsurance broker to benchmark loads across jurisdictions and negotiate better terms. The actuary who ran the comparison was able to show his carrier's management that the Texas load was out of line with what carriers in other markets paid. That data gave the carrier leverage in its next treaty negotiation. The carrier was able to reduce its load from 18 percent to 15 percent by threatening to move the block to a different reinsurer.
Product design can also reduce reliance on high-load reinsurance. A carrier can structure a term life policy with a shorter initial guarantee period or a graded death benefit, reducing the net amount at risk in the early years and thus the amount ceded to reinsurers. For disability riders, the carrier can self-insure a portion of the risk by retaining a higher deductible or a longer elimination period. These design choices trade off consumer appeal for lower reinsurance costs.
Finally, a carrier can explore alternative risk transfer mechanisms such as insurance-linked securities or catastrophe bonds for mortality risk. While these are more common in property catastrophe lines, there is growing interest in life securitization. The actuary's comparison shows that the potential savings are large enough to justify the upfront cost of structuring such a transaction. The carrier that does it first in Texas may gain a meaningful pricing advantage over competitors that stick with traditional reinsurance.
Conclusion: Market Structure as a Pricing Driver
The 40 percent spread in reinsurance load between Germany and Texas is not an anomaly. It reflects deep structural differences in how two markets organize risk transfer. Germany's pooled system produces lower, more stable loads at the cost of some underwriting flexibility. Texas's fragmented market yields higher loads that vary widely, with the burden falling disproportionately on smaller carriers and their policyholders. Neither system is perfect, but the comparison highlights a clear trade-off: pooling reduces consumer premiums but may dampen competitive differentiation, while fragmentation preserves carrier choice but inflates costs.
For regulators, the spread raises questions about whether the current U.S. approach serves consumers well. For carriers, it offers a benchmark to push for better terms. For the actuary who ran the numbers, it was a reminder that the most important pricing factors are often not the risk itself but the rules of the market in which that risk is priced. His analysis, while anonymous, provides a rare glimpse into a component of premium that most consumers never see—and that most carriers prefer to keep that way.