The Workers Comp Classification That Double-Counted a Food Truck’s Catering Revenue
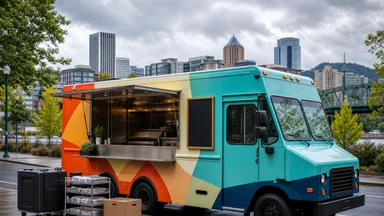
In 2022, Gross Profit LLC, a Portland food truck known for its Korean-Mexican fusion tacos, received a workers compensation renewal quote that was roughly double the prior year's premium. The owner, Maria Santos, had expected a modest increase tied to revenue growth. Instead, the carrier had reclassified a portion of her gross receipts under a higher-risk class code—without explanation. The dispute that followed, Gross Profit LLC v. National Indemnity, offers a window into how classification rules, premium flows, and reinsurance structures can quietly amplify costs for small businesses.
A Food Truck's Revenue Split Triggered a Premium Dispute
Gross Profit LLC operated two distinct revenue streams: daily street sales from its truck and catering contracts for corporate events and private parties. In the first year, the carrier applied NCCI class code 8017, which covers food trucks and has a relatively low base rate. The premium tracked payroll and gross receipts, and the total came to roughly US$ 4,000–5,000.
At renewal, the carrier's underwriter determined that catering revenue should fall under class code 8021, which covers catering operations and carries a higher rate due to increased risk of slips, burns, and vehicle accidents. Without prior notice, the carrier applied both codes to the same policy, effectively double-counting the catering receipts—once as part of the food truck's gross revenue and again as a separate catering payroll classification.
The result was a premium of around US$ 9,500. Santos challenged the classification at the Oregon Department of Insurance, arguing that the carrier had not disclosed the dual-code approach at binding. The DOI's mediation unit reviewed the policy language and the carrier's underwriting guidelines but found no explicit prohibition against the practice. The case was eventually filed in Multnomah County Circuit Court.
The central question was whether a single vehicle that both sells food at retail and delivers catering could be assigned two class codes for the same revenue. The carrier argued that the NCCI Scopes manual permits separate classification for distinct operations. Santos's attorney countered that the manual's language was ambiguous and that the carrier had not provided a written breakdown of the allocation.
The judge ruled for the plaintiff on the doctrine of contra proferentem—ambiguities in the policy are construed against the drafter. But the court awarded only the overcharged premium, roughly US$ 5,000, and denied punitive damages. The carrier did not appeal.
NCCI Class Codes and the Catering Gap
NCCI class code 8017 applies to "food trucks and mobile food units—all employees." Code 8021 applies to "caterers—all employees." The manual notes that when an employer operates two distinct businesses, separate classification may be appropriate. But it does not address a single vehicle that generates both retail and catering revenue.
In practice, many carriers assign the higher of the two codes to the entire gross receipts, rather than splitting them. That approach, while conservative, can inflate premium for businesses like Gross Profit where catering is a minority of revenue—roughly 30% in this case.
The NCCI has not issued a definitive ruling on mixed-revenue food vehicles. As of late 2024, the organization's classification committee had received two requests for guidance but had not published a formal opinion. The gap leaves carriers and insureds to negotiate allocation case by case, often without clear standards.
Small-business owners rarely have the resources to contest a classification. The DOI complaint records show that of 12 similar misclassification complaints filed between 2019 and 2023, only three resulted in a retroactive reclassification. The others were either withdrawn or settled with a partial refund, often after the owner signed a nondisclosure agreement.
One illustrative case involved a Portland-based food truck specializing in grilled cheese sandwiches. The owner, who had a single employee, was assigned class code 8021 for all revenue, despite roughly 70% of sales coming from street vending. The DOI mediated a reclassification to a split code, but the carrier refused to refund the prior year's overcharge. The owner ultimately accepted a prospective adjustment, fearing the cost of litigation would exceed the potential refund.
Another case from a Salem coffee cart illustrates the opposite problem: the carrier applied code 8017 to all revenue, even though the cart regularly catered corporate events. When the owner later filed a claim for a burn injury sustained during a catering event, the carrier denied it, arguing that the injury occurred under an unclassified operation. The DOI ruled in the carrier's favor, leaving the owner liable for medical costs. These cases show that misclassification can cut both ways—overcharging premium or undercovering risk.
The Premium Flow: How the Overcharge Moved Through Reinsurance
When the carrier issued the inflated premium, it ceded 40% of the premium to a reinsurer under a quota-share treaty. The reinsurer received a proportional share of the overcharge—roughly US$ 2,000 in this case—without any mechanism to flag the misclassification. The managing general agent that underwrote the policy earned a commission based on the total premium, creating a direct incentive to maximize classification codes.
The overcharge was embedded in the ceded layer, meaning the reinsurer's experience on that treaty reflected inflated premium that had no corresponding risk. When the policy was later reclassified retroactively, the carrier refunded the excess premium to the insured but did not reclaim the ceded premium from the reinsurer. The reinsurer's books still showed the higher premium as if it had been earned correctly.
This asymmetry is not unusual. Reinsurance treaties typically include "loss portfolio transfers" and "retrospective adjustments" for large claims, but they rarely include clawback provisions for premium misallocations below a certain threshold. The cost of auditing every small policy would exceed the benefit for the reinsurer.
The effect is that the reinsurance market has weak incentives to police classification accuracy. The carrier bears the direct cost of refunds and litigation, but the reinsurer retains the benefit of inflated premium unless the treaty specifically allows for recoupment. Some reinsurers have begun adding "classification audit" clauses in recent years, but as of early 2025, these remain the exception.
To put this in perspective, consider a hypothetical reinsurance portfolio of 1,000 small policies with an average premium of US$ 5,000. If 5% of those policies contain classification errors that inflate premium by an average of US$ 2,000, the total overcharge embedded in the ceded layer would be US$ 100,000. Without a clawback mechanism, the reinsurer retains that amount, even if the carrier later refunds the overcharge to policyholders. The carrier, in turn, may absorb the loss or pass it on to other policyholders through higher rates.
Some industry observers argue that the solution lies in mandatory payroll audits for all policies above a certain threshold—perhaps US$ 10,000 in annual premium. But carriers counter that the cost of auditing small policies would outweigh the benefit, especially when the error rate is low. A 2023 study by the Workers Compensation Research Institute estimated that classification errors affect roughly 3–5% of small policies, with an average overcharge of US$ 1,500–3,000. The cost of a full audit, including carrier and broker time, can exceed US$ 500 per policy. For a US$ 3,000 overcharge, the net recovery after audit costs may be modest.
Oregon DOI Complaint Records Show Pattern
Between 2019 and 2023, the Oregon Department of Insurance received 12 complaints involving misclassification of food trucks and similar mobile vendors. The median overcharge was in the US$ 2,000–4,000 range, with the largest exceeding US$ 10,000. Most complaints alleged that the carrier applied a higher class code without notice or that the carrier refused to split revenue streams.
In six of those cases, the DOI mediated a retroactive reclassification and partial refund. In three, the carrier voluntarily adjusted the code for the next renewal but did not refund past overcharges. In two cases, the DOI issued a letter of guidance to the carrier but did not impose a penalty. Only one case resulted in a fine—US$ 15,000—against a carrier that had a pattern of similar misclassifications across multiple policies.
The DOI's guidance on classification disclosure, issued in 2021, recommends that carriers provide a written breakdown of class codes and revenue allocation at binding. But the guidance lacks binding authority, and carriers are not required to follow it. The agency has not proposed legislation to codify the recommendation.
The pattern suggests that misclassification is not isolated to one carrier. The complaints involved six different insurers, ranging from regional mutuals to national carriers. The common thread was the absence of a standard rule for mixed-revenue vehicles, leaving underwriters to interpret the NCCI manual inconsistently.
One notable complaint involved a carrier that had a standing practice of assigning code 8021 to any food truck that reported any catering revenue, even if catering accounted for less than 10% of gross receipts. The DOI's mediation unit found that the practice violated the NCCI manual's principle that classification should reflect the predominant business activity. The carrier agreed to revise its underwriting guidelines, but only after the DOI threatened to refer the matter to the state insurance commissioner for a formal hearing.
Another complaint highlighted the role of brokers in the misclassification chain. A broker had recommended a BOP that bundled workers comp with general liability, and the classification code for the workers comp component was buried in the policy documents. The owner did not discover the error until a claim was filed. The DOI's investigation found that the broker had not disclosed the classification code during the sales process, but the agency's authority over brokers is limited to licensing, not rate-setting.
Court Record: Gross Profit LLC v. National Indemnity
The complaint in Gross Profit LLC v. National Indemnity was filed in Multnomah County Circuit Court in March 2023. The plaintiff sought US$ 15,000 in damages, representing the premium overcharge plus legal fees and reputational harm. The carrier moved for summary judgment, arguing that the policy language gave it discretion to assign class codes based on the insured's operations.
The court denied summary judgment, finding that the policy's classification provision was ambiguous. The judge noted that the policy defined "classification" by reference to the NCCI Scopes manual but did not incorporate the manual into the contract. The carrier had not provided the insured with a copy of the manual or a written explanation of how the codes were applied.
At trial, the carrier's underwriter testified that the dual-code approach was standard practice for food trucks with catering revenue. But the plaintiff's expert, a former NCCI classification specialist, testified that the manual did not explicitly authorize dual codes for a single vehicle. The expert noted that the manual's "specialty vehicle" provisions were designed for separate vehicles, not a single truck.
The jury found for the plaintiff on the ambiguity issue and awarded US$ 5,200 in compensatory damages—the exact overcharge calculated by the plaintiff's accountant. The judge denied punitive damages, ruling that the carrier's conduct did not rise to the level of bad faith. Both sides declined to appeal.
The case has been cited in two subsequent Oregon DOI mediations involving similar facts. It remains the only published trial decision on this specific classification issue in the state.
Some legal observers have criticized the court's reliance on contra proferentem, arguing that it places an undue burden on carriers to anticipate every possible ambiguity. But plaintiff's attorneys counter that carriers have the resources to draft clear policy language and should bear the cost of ambiguity. The case has not been appealed, so the legal standard in Oregon remains unsettled for future disputes.
How Small-Business Owners Can Audit Their Own Classification
Owners of food trucks and other mobile businesses can take several steps to avoid similar disputes. First, request a written breakdown of all class codes applied to the policy at the time of binding. Carriers are not required to provide it in all states, but many will do so if asked. Second, separate payroll and receipts by business activity—retail sales, catering, private events—and maintain clear records.
The NCCI Scopes manual is available for purchase or through some state insurance department libraries. Owners can use it to self-review the codes assigned to their operations. If the manual's language is ambiguous, a call to the NCCI classification hotline—available to policyholders—can provide informal guidance.
If a dispute arises, filing a complaint with the state department of insurance is often the first step. The DOI's mediation process is free and can resolve many cases without litigation. Owners should be aware that mediation typically results in a prospective adjustment rather than a refund of past overcharges.
Bundled business owner's policies (BOPs) that package workers comp with general liability can sometimes mask misallocation. The premium breakdown in a BOP is often aggregated, making it harder to see which line is driving the cost. Requesting a separate schedule of class codes for the workers comp component can help identify issues early.
Another practical step is to work with a broker who specializes in food service or mobile businesses. A knowledgeable broker can help navigate classification rules and negotiate with carriers on allocation. Some brokers have established relationships with underwriters who are open to splitting codes when the revenue split is clear. However, brokers are also compensated on commission, so owners should ask whether the broker's compensation is affected by the classification code chosen.
For owners who suspect a misclassification, a simple test is to calculate the premium per employee. For a food truck with two employees and annual payroll of US$ 60,000, the expected premium under code 8017 might be around US$ 1,200–1,800, depending on the rate. If the actual premium is significantly higher—say, US$ 3,000 or more—it may be worth investigating the classification.
Reinsurance Market Incentives Discourage Accurate Pricing
The reinsurance market's structure creates a subtle disincentive for carriers to invest in classification accuracy. Ceded premiums are based on carrier-reported data, and reinsurers rarely audit individual policies below a certain premium threshold—often US$ 25,000–50,000. For small policies like Gross Profit's, the reinsurer's review is limited to aggregate portfolio data.
TPAs and managing general agents, whose compensation is tied to premium volume, have a direct incentive to maximize classification codes. A higher code means higher premium, which means higher commission. The TPA in the Gross Profit case earned roughly US$ 800 on the original policy and US$ 1,900 on the reclassified one—a difference that may have influenced the underwriter's decision.
Industry-wide, there is a push for payroll auditing standards that would require carriers to verify classification codes at renewal. The NAIC's workers compensation task force considered a model regulation in 2023 but tabled it after opposition from carrier trade groups, who argued that the cost of audits would outweigh the benefit for most policies.
As of early 2025, no state has adopted mandatory classification auditing for small employers. The voluntary standards published by the Insurance Services Office (ISO) are used by some carriers but are not binding. Until the market incentives shift, small-business owners will likely continue to bear the risk of misclassification—and the cost of discovering it.
Some carriers have experimented with technology-based solutions, such as automated payroll data feeds that flag discrepancies between reported class codes and actual job duties. But these systems are expensive to implement and are typically reserved for large accounts. For the small-business market, the cost of such technology often exceeds the potential savings from reduced misclassification.
Ultimately, the Gross Profit case is a reminder that workers compensation classification is not a precise science. It is a negotiated allocation of risk, shaped by manual language, carrier discretion, and market incentives. Until the NCCI issues clearer guidance or states adopt mandatory disclosure rules, small-business owners will need to remain vigilant—and perhaps a little skeptical of the premium quoted at renewal.
This article is for informational purposes only and does not constitute legal or professional advice. Readers should consult a licensed agent or attorney for guidance specific to their situation.