A New York Auto Rate Filing Rejected Ceded Commission on a Fleet Block
In early 2025, a New York auto insurer submitted a rate filing for a fleet block that proposed a 12% increase based on loss trends. The filing included a quota share reinsurance treaty under which 30% of premium was ceded to a reinsurer at a 5% ceding commission. The New York Department of Financial Services rejected the filing, arguing that the ceding commission inflated the net premium retained by the direct writer, making the rate increase appear smaller than justified. The rejection signals a growing regulatory focus on how reinsurance costs are treated in rate filings, particularly when commissions lack documented service justification.
The Filing That Got Rejected
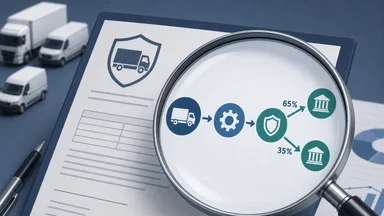
The insurer, a regional carrier with a book of commercial fleet business, filed for a 12% rate increase on a block of roughly 2,000 vehicles — delivery vans, service trucks, and light commercial autos. The filing cited a loss ratio that had crept above 70% over two years, driven by increased claim severity in urban areas. To support the increase, the insurer attached a quota share reinsurance agreement that ceded 30% of premium at a 5% ceding commission.
The DFS actuary reviewing the filing flagged the ceding commission as problematic. Under the treaty, the reinsurer received 30% of gross premium but paid back 5% of that ceded premium as a commission — effectively reducing the reinsurer's net cost. The regulator calculated that the commission made the net premium retained by the direct writer roughly 1.5% lower than it would be without the commission, meaning the true rate need was closer to 13.5–14%.
The insurer argued that the commission reflected services provided by the reinsurer — claims handling and underwriting support — but provided no documented evidence. The DFS rejected the filing, citing lack of transparency. The decision was not final; the insurer could refile with a revised structure or justification, but the rejection set a precedent for similar deals in New York.
How Ceded Commission Shifts Premium Flow
Ceding commission is a fee the direct insurer pays to the reinsurer, typically as a percentage of ceded premium. In a quota share treaty, the reinsurer assumes a fixed share of premium and losses. The commission is meant to cover the reinsurer's acquisition costs — but when it is not tied to actual services, it can shift profit from the direct writer to the reinsurer.
In this fleet block, the 5% ceding commission meant the reinsurer effectively paid only 95% of the ceded premium for its share of the risk. The direct writer, in turn, retained 70% of gross premium but netted a slightly larger share because the commission reduced the ceded amount. The net effect was a lower apparent loss ratio on the retained block, making the rate increase look smaller than the underlying loss trend warranted.
Actuaries call this a premium-flow distortion. The commission does not change the total premium collected from policyholders, but it reallocates how that premium is split between direct writer and reinsurer. For the regulator, the key question is whether the commission represents a real expense or a disguised profit transfer. In this case, the DFS concluded it was the latter.
Similar dynamics appear in other lines. A related article on this site compared a German term life rate to a Texas one and found a 40% spread in the reinsurance load, illustrating how cross-border differences in ceding commissions can affect pricing.
Fleet Auto Reinsurance Mechanics
Fleet auto reinsurance often uses quota share treaties because the risk pool is relatively homogeneous — many vehicles of similar type and use. The quota share percentage is typically 20–50%, depending on the direct writer's risk appetite and capital position. In this filing, the 30% cession was within normal range.
The 5% ceding commission, however, was high for a fleet block. Typical commissions for commercial auto quota shares range from 1–3%, reflecting minimal services — the reinsurer often relies on the direct writer's underwriting and claims handling. A 5% commission would be more common for a new or niche program where the reinsurer provides significant expertise.
Under the treaty, the reinsurer paid claims proportionally — 30% of each loss — but its net retention after commission was effectively 28.5% of gross premium. That 1.5% gap (30% ceded minus 28.5% net retention) went to the reinsurer as a fee. The direct writer's net retention was 71.5% (70% plus the 1.5% reduction in ceded premium). The loss ratio on the retained block appeared 1–2 points lower than the gross loss ratio, masking the true deterioration.
The DFS actuary recalculated the rate need by removing the commission, which increased the required rate change from 12% to roughly 14.5%. The insurer had not accounted for this in the filing, and the regulator viewed the omission as a material flaw.
Regulatory Scrutiny on Reinsurance Costs
New York's DFS has long required rate filings to be transparent about all costs, including reinsurance. The state's insurance law mandates that rates not be excessive, inadequate, or unfairly discriminatory. Ceded commissions that inflate net premium can make rates appear inadequate on paper, but the regulator's concern is broader: that the commission structure misleads policyholders and distorts competition.
This rejection follows a pattern. In 2023, the DFS rejected a similar filing for a workers' compensation block where a 4% ceding commission was labeled as a "service fee" but no services were documented. The regulator issued a bulletin in 2024 reminding insurers that ceded commissions must reflect actual services rendered and must be justified in the rate filing.
The bulletin, while not legally binding, signals the DFS's stance. Insurers must now provide detailed descriptions of the services the reinsurer provides — claims handling, underwriting, actuarial support — and how the commission amount relates to the cost of those services. Without such documentation, commissions above 2–3% are likely to face rejection.
Precedent matters. Other states, including California and Texas, have issued similar guidance, but New York's enforcement is notably strict. The rejection in this fleet auto filing may prompt other regulators to scrutinize ceded commission structures more closely, particularly in commercial lines where quota share treaties are common.
Impact on Premium and Solvency
Without the ceding commission, the direct writer's net premium from the fleet block increases by about 1.5%. That may sound small, but on a $10 million gross premium block, it amounts to $150,000. The insurer must also hold higher unearned premium reserves because the net premium is larger, leading to surplus strain.
The original 12% rate increase was calculated assuming the ceding commission would persist. After the rejection, the insurer must either refile at a higher rate — perhaps 14–16% — or restructure the reinsurance to eliminate or reduce the commission. Either option affects the insurer's bottom line and could make the fleet block less attractive to write.
For the reinsurer, the rejection may shift pricing. If ceding commissions are capped at 2–3%, the reinsurer's net cost increases, potentially leading to higher reinsurance rates or lower capacity for fleet auto. Some reinsurers may exit the market if they cannot earn the expected return.
Surplus strain is a particular concern for smaller regional carriers. A 5% reduction in ceded premium means more capital must be allocated to support the retained risk. This can constrain growth or force the insurer to seek additional capital, which is costly. The rejection effectively raises the cost of doing business for the direct writer, even if the rate increase is ultimately approved.
What This Means for Fleet Underwriters
Fleet auto underwriters must now consider reinsurance structure as part of rate development. A filing that includes a ceding commission should be stress-tested: what is the needed rate if the commission is disallowed? The answer could be a 2–3 percentage point difference, which is material in a competitive market.
Actuaries should model regulatory rejection scenarios as part of the pricing process. If the commission is above 2%, the probability of rejection is higher, and the filing should include a contingency plan. Some insurers are already moving to lower commissions or structuring them as expense reimbursements with clear documentation.
The New York filing may set a precedent for other states. If the DFS's reasoning is adopted elsewhere, ceded commission caps could become an industry standard. This would reduce the flexibility of quota share treaties but also increase transparency in rate filings.
For fleet underwriters, the key takeaway is to separate commission from rate need. The commission is a cost, not a profit center, and should be justified as such. A related article on this site highlighted a Quebec contractor who paid a French professional indemnity rate but was defended under New York law, showing how jurisdictional differences in reinsurance treatment can create pricing mismatches.
Takeaways for Pricing and Compliance
First, document all reinsurance commissions with a clear service justification. If the reinsurer provides no services, the commission should be zero. If services are provided, the commission should be tied to the cost of those services, not a fixed percentage of premium.
Second, rate filings should include sensitivity analysis showing how the required rate changes with different commission levels. This allows the regulator to see the impact and reduces the chance of rejection. The insurer in this case could have avoided rejection by including such analysis.
Third, monitor DFS bulletins and other state regulatory guidance. The 2024 bulletin was a warning; more may follow. Insurers that proactively adjust their ceding commission structures will face fewer regulatory hurdles.
Fourth, expect more rejections if commissions exceed 2–3% without strong justification. The market may shift toward lower commissions or alternative structures such as profit commissions or contingent commissions tied to loss experience.
Finally, fleet auto rates may rise faster than anticipated due to this regulatory friction. The 12% increase that was filed might have been adequate if the commission were justified, but after rejection, the true rate need is higher. Policyholders will ultimately bear the cost, but the process ensures that rates reflect actual risk rather than accounting structures.
Counter-Arguments and Trade-Offs
Not everyone agrees with the DFS's approach. Some industry actuaries argue that ceding commissions, even without explicit service documentation, are a legitimate component of reinsurance pricing. In a competitive reinsurance market, they say, the commission simply reflects the net cost of transferring risk. If the reinsurer is willing to accept a lower net premium in exchange for a commission, that is a market price, not a distortion. The regulator, they contend, should focus on the overall rate adequacy rather than dissecting the components.
There is also a practical trade-off. Requiring detailed service justification for every commission increases compliance costs and slows down rate filings. For smaller insurers with limited actuarial staff, this could be a significant burden. They may be forced to use simpler reinsurance structures, which could reduce their ability to manage risk efficiently.
Another counter-argument is that the DFS's stance may push reinsurance business to less regulated markets. If New York makes it too costly to use ceding commissions, reinsurers might shift capacity to other states or to offshore entities, reducing competition in the local market. This could ultimately hurt policyholders if it leads to higher premiums or fewer options.
However, the DFS's position has support from consumer advocates who argue that opaque reinsurance costs allow insurers to hide profits and justify unnecessary rate increases. They point to cases where ceding commissions were used to shift profits to affiliated reinsurers, effectively bypassing rate regulation. The transparency requirement, they say, is a necessary check on such practices.
Looking Ahead: Ceding Commission Caps and Alternatives
Looking forward, the industry may see a move toward explicit caps on ceding commissions in rate filings. Some states are considering regulations that limit commissions to a fixed percentage of ceded premium, say 2%, unless the insurer can demonstrate a higher amount is justified. This would simplify the filing process and reduce regulatory disputes.
Alternative structures are also gaining attention. Profit commissions, where the reinsurer shares in the underwriting profit of the block, can align incentives without distorting premium flow. Contingent commissions tied to loss experience are another option. These structures are more complex to model but may face less regulatory resistance because they are clearly tied to performance.
For the fleet block in question, the insurer is likely to refile with a lower ceding commission — perhaps 2% — and provide documentation for the services rendered. The DFS may approve a rate increase closer to 14% if the insurer can justify the loss trends. The episode serves as a case study for the entire industry: reinsurance structure is no longer a back-office detail but a front-line regulatory issue.
This article is for informational purposes only and does not constitute professional actuarial or legal advice. Insurers should consult with qualified professionals regarding specific rate filings and regulatory compliance.