Telematics Pricing on a German Autobahn Policy Clashed With a Nebraska Rate Filing
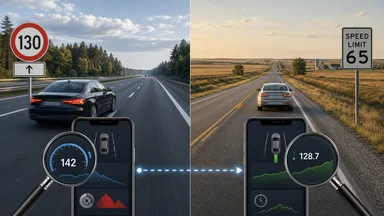
Telematics insurance—where a smartphone app or plug-in device tracks driving behavior—promises to personalize premiums based on actual risk. But when the same product architecture meets the German Autobahn and a Nebraska state filing, the pricing outcomes diverge sharply. The Autobahn policy, with no federal speed cap, weights speed exceedances heavily; the Nebraska filing, shaped by regulatory prior approval and lower speed limits, emphasizes mileage and time of day. This cross-jurisdiction comparison reveals how local regulation, driving culture, and actuarial tradition produce two distinct products from the same technological core.
Why the Same Telematics Product Priced Differently in Munich and Omaha
Usage-based insurance (UBI) relies on a common data set: GPS location, speed, acceleration, braking, and time of day. Insurers in both Germany and Nebraska collect similar signals from dongles or smartphone apps. Yet the premiums that emerge differ by more than the exchange rate would suggest.
In Germany, an insurer like HUK24 offers a telematics discount that can reach 30% of the base premium for safe driving. The program tracks harsh braking, rapid acceleration, and—critically—speeds above 130 km/h (roughly 80 mph), even on sections of Autobahn where no binding speed limit exists. The actuarial model treats high speed as a severe-loss predictor, increasing the risk load for any trip that exceeds advisory limits.
In Nebraska, the same telematics data might feed a mileage-based plan from State Farm or Progressive. The Nebraska Department of Insurance requires that any rating factor—including telematics scores—be actuarially justified in a public filing. Speed is a factor, but it is tempered by the state’s enforcement of speed limits (typically 75 mph on interstates) and the prevalence of rural roads where weather and distance matter more than velocity.
The divergence is not merely academic. It affects how insurers build their rating engines, how they communicate with regulators, and ultimately what the customer pays. As one actuary put it, “You can’t just export a telematics algorithm from Munich to Omaha and expect it to work.”
Consider a concrete example: a driver who commutes 30 miles each way on a highway with a 75 mph speed limit. In Nebraska, that driver’s telematics score might be penalized for mileage but not for speed, since 75 mph is within the legal limit and typical traffic flow. In Germany, the same distance on an unrestricted Autobahn section could see the driver traveling at 150 km/h (93 mph), triggering a speed penalty that raises the premium for the entire month. The same behavior—high-speed highway driving—produces opposite pricing outcomes because the regulatory and cultural contexts differ.
German Telematics: Pricing Without a Federal Speed Cap
Germany’s Autobahn network includes stretches with only an advisory speed limit of 130 km/h. Driving faster is legal, but for insurers, it creates a unique risk profile. Claims data from German insurers shows that while accident frequency is not significantly higher at speeds above 130 km/h, severity—measured in average payout per claim—jumps sharply.
Telematics programs like HUK24’s “Telematik Plus” use a smartphone app to record speed, acceleration, and braking. The app assigns a score each trip, and the monthly premium adjusts accordingly. A driver who consistently stays below 130 km/h and avoids harsh events can see a discount of up to 30%. But a single high-speed trip can raise the score for the entire month.
BaFin, the German financial regulator, permits this dynamic pricing but requires transparency: insurers must disclose the scoring algorithm in general terms, and policyholders can opt out of telematics and revert to a standard rate at any time. This opt-out provision is a consumer protection feature that also limits how aggressively insurers can price risk.
German insurers have argued that speed-based telematics reduces accidents by encouraging slower driving. Critics counter that the high-speed risk is concentrated among a small number of drivers, and that the discounts mostly reward those who would drive safely anyway. Still, the market has embraced the model: roughly 15% of German auto policies now include a telematics component, according to industry estimates as of late 2024.
One trade-off that German insurers face is the potential for adverse selection. Drivers who know they drive at high speeds may opt out of telematics entirely, leaving the program populated by safer drivers. This can inflate the discount offered to telematics participants, because the risk pool is artificially low. To counter this, some insurers adjust the base rate for non-telematics policies upward, effectively cross-subsidizing the telematics discount. BaFin monitors this practice to ensure that standard rates are not excessive.
Nebraska’s Rate Filing: How State Regulation Shapes UBI
In Nebraska, telematics insurance must pass through a different regulatory sieve. The Nebraska Department of Insurance requires prior approval of all rates, meaning an insurer must file its rating plan—including any telematics-based discounts or surcharges—and receive explicit approval before using it.
The filing must demonstrate that each rating factor is actuarially sound. For a telematics plan, that means showing a statistical relationship between the measured behaviors (mileage, braking events, time of day) and claim costs. Speed is a factor, but Nebraska’s speed limits (typically 65-75 mph on highways) compress the range of speeds, reducing its predictive power relative to mileage.
Winter weather and rural roads introduce additional complexity. A driver in western Nebraska might log many miles on icy, two-lane highways, while a driver in Omaha faces urban congestion. Telematics can capture these differences, but the filing must justify how each variable is weighted. Some insurers have chosen to limit telematics to mileage-only plans to simplify the regulatory review.
State Farm, for example, offers a “Drive Safe & Save” program in Nebraska that uses a plug-in device to track mileage and some driving events. The program is filed as a tiered discount plan: drivers who drive less and brake gently get a larger discount. But the discount is capped at a fixed percentage, and the base rate remains unchanged for the policy term. This rigidity contrasts with the German model, where premiums can fluctuate monthly.
Another Nebraska-specific challenge is the treatment of seasonal driving patterns. Farmers and ranchers may drive heavily during planting and harvest seasons but very little in winter. A telematics plan that averages mileage over a year might penalize them unfairly. Progressive’s “Snapshot” program in Nebraska addresses this by allowing policyholders to earn discounts based on a short monitoring period (typically 30-90 days) and then locking in the discount for the policy term. This approach avoids the complexity of continuous monitoring but may not capture long-term behavior changes.
The Actuarial Gap: Mileage vs. Speed as Primary Rating Factor
The core actuarial difference between the two markets lies in which variable dominates the risk model. In Germany, speed is the strongest predictor of claim severity. A study published by the German Insurance Association (GDV) in 2023 found that trips with average speeds above 130 km/h had claim costs roughly 40% higher than trips at 100-120 km/h, after controlling for distance and driver age.
In the United States, the Insurance Institute for Highway Safety (IIHS) has published research showing that annual mileage is the single best predictor of claim frequency, and that hard braking events (a proxy for following too closely) correlate with both frequency and severity. Speed is a factor, but its effect is muted by enforcement and road design.
These differences are not just statistical artifacts; they reflect real driving environments. On the Autobahn, a driver can legally travel at 200 km/h, creating potential for catastrophic collisions. In Nebraska, the highest legal speed is 80 mph (about 129 km/h), and actual travel speeds rarely exceed 85 mph due to enforcement. The same telematics algorithm that flags a 90 mph event as high-risk in Nebraska would treat it as moderate in Germany.
Insurers operating in both markets must therefore build separate actuarial models. Octo Telematics, a global UBI platform provider, has developed localized scoring algorithms for its clients. The German version weights speed exceedances above 130 km/h as a 30% factor; the North American version weights hard braking and mileage at 40% combined. No single telematics score works across jurisdictions.
A counter-argument worth considering: some actuaries argue that the predictive power of speed is overstated in Germany because the data is confounded with road type and traffic density. High-speed driving on the Autobahn often occurs on straight, well-maintained roads with low traffic, which might actually be safer than slower driving on congested urban roads. If that is the case, then penalizing speed could unfairly target drivers who are actually at lower risk. German insurers have begun to explore multi-factor models that adjust for road type, but these are not yet widespread.
Regulatory Divergence: BaFin’s Flexibility vs. Nebraska’s Scrutiny
The regulatory environments for telematics differ in several key dimensions. BaFin allows real-time premium adjustments within a contract period, provided the insurer notifies the policyholder and offers an opt-out. This flexibility lets German insurers experiment with dynamic pricing and adjust discounts based on recent driving data.
Nebraska law, by contrast, prohibits mid-term rate changes based on driving data. Once a policy is issued, the premium is fixed for the term—typically six or twelve months. If a driver’s telematics data shows deteriorating behavior, the insurer must wait until renewal to adjust the rate. This constraint reduces the incentive for insurers to invest in real-time monitoring, since the data cannot immediately affect revenue.
Another difference: German insurers must offer a standard (non-telematics) rate to any customer who opts out, and that standard rate cannot be higher than the rate that would apply without telematics. This prevents insurers from using telematics as a way to segment high-risk drivers into higher-priced non-telematics plans. In Nebraska, there is no such requirement; an insurer could, in theory, offer telematics only to good drivers and charge others a higher standard rate, though anti-discrimination laws limit this practice.
The compliance costs also differ. Filing a telematics plan in Nebraska requires an actuarial memorandum, data supporting each factor, and a public hearing if the filing is challenged. In Germany, the process is less formal: the insurer must notify BaFin of the product terms but does not need prior approval for each rating factor, as long as the overall premium is adequate and not excessive.
These regulatory differences affect product profitability. A German telematics policy might have lower compliance costs but higher churn due to monthly premium fluctuations. A Nebraska policy might have higher fixed costs from filing but more stable customer retention. The trade-off is real, and insurers entering either market must weigh it carefully.
For example, a mid-sized German insurer can launch a telematics product with a small actuarial team and minimal regulatory paperwork. In contrast, a U.S. insurer targeting Nebraska must budget for a multi-month filing process and potentially a public hearing if consumer groups object. This asymmetry can discourage smaller players from entering the Nebraska market, reducing competition.
What the Clash Reveals About Telematics Standardization
The clash between the German Autobahn policy and the Nebraska rate filing underscores a broader truth: telematics insurance is inherently local. Global platforms like Octo or Cambridge Mobile Telematics provide the hardware and software, but the rating engine must be tailored to each jurisdiction’s driving patterns, claims experience, and regulatory constraints.
Efforts to standardize telematics scoring across markets have so far failed. The International Organization for Standardization (ISO) has published a framework for UBI data collection (ISO 24100), but it does not prescribe how to weight variables. The European Union’s General Data Protection Regulation (GDPR) imposes additional privacy requirements that affect how data can be used in scoring, further differentiating EU products from U.S. ones.
Some observers argue that as more data accumulates, a global standard may emerge. Insurers could share anonymized data to build a universal risk model, similar to the way credit scoring agencies operate. But privacy laws and competitive concerns make this unlikely in the near term.
Others contend that the divergence is permanent. Driving is a cultural activity as much as a physical one. German drivers accept speed-based pricing because they see the logic; American drivers may resist it as intrusive. Until consumer attitudes converge, telematics products will remain fragmented.
Consider the cultural dimension: in Germany, there is a long tradition of speed-related risk awareness, reinforced by driver education and Autobahn signage. In the U.S., speed limits are widely seen as arbitrary, and many drivers routinely exceed them. A telematics product that penalizes speeding may be viewed as unfair in a market where speeding is common and enforcement is inconsistent. This cultural resistance can lead to lower uptake and higher opt-out rates, undermining the viability of speed-based UBI in the U.S.
Practical Takeaways for Insurers Operating in Both Markets
For insurers that operate in both Germany and the United States—like Allianz or Zurich—the lesson is to build modular rating engines that can swap factor weights per state or per country. A single telematics platform can collect the same data streams, but the algorithm that converts data into a score must be a configurable module, not a hard-coded function.
Engaging local regulators early in the product design phase is essential. In Nebraska, that means filing a draft rating plan with the Department of Insurance and soliciting feedback before committing to a system. In Germany, it means discussing with BaFin how the scoring algorithm will be disclosed and how the opt-out mechanism will work.
Insurers should also invest in separate actuarial teams for EU and U.S. filings, because the statistical methods differ. German actuaries are comfortable with generalized linear models that treat speed as a continuous variable; U.S. actuaries often prefer tiered models that group drivers into buckets. The choice affects how telematics data is transformed into rates.
One promising area: using Nebraska’s low-speed telematics data to pilot rural UBI programs. The state’s long, straight roads and predictable weather patterns make it an ideal test bed for mileage-based models that could later be adapted to other U.S. states. Similarly, German speed data can inform severe-loss models for high-speed driving in other markets, such as parts of the Middle East or Australia.
Another practical insight: insurers should consider hybrid models that combine telematics with traditional rating factors. For example, a policy could use telematics to adjust the premium within a band of plus or minus 10%, while the base rate is determined by age, location, and vehicle type. This approach reduces the volatility that can scare off consumers while still capturing some behavioral risk. In Germany, some insurers have moved to this model to address churn concerns.
Finally, insurers should monitor the evolution of speed-based metrics in Germany to refine their global models. As electric vehicles become more common—and as autonomous driving features reduce human error—the relative importance of speed may shift. The German market, with its high-speed tolerance, will likely be the first to show how telematics pricing adapts.
The clash between a German Autobahn policy and a Nebraska rate filing is not an anomaly; it is a preview of the challenges that await any globally-minded insurer in a world of locally regulated risk. The data is global, but the price is local—and that gap is where the actuarial work begins.
This article is for informational purposes only and does not constitute professional actuarial or regulatory advice. Insurers should consult qualified professionals for product design and rate filings.